Our Credit Risk Analytics practice specialises in the development and validation of credit risk models across IRB, IFRS 9, and IFRS 9 stress testing. Portfolio credit risk support is available for selected topics. Engagement can be supplemented with model risk review and prototypical programming to support end-to-end delivery. An outline of our services is displayed below.
For inquiries on support towards a succesful project outcome and consultancy - contact us directly.
→ Contact
Disclaimer: Data and commentary displayed herein are for information purposes only and do not provide any consulting advice. No information provided in this documentation shall give rise to any liability of Auriscon HK Ltd and Auriscon Ltd.
At Auriscon, we bring the right expertise, working on-site or remotely based on flexible arrangements:
-
Confidential handling of methodology and analytical models
-
Business insight translated into tailored solutions
-
Industry standards and emerging risks clearly addressed
We help clients navigate challenging regulatory and market environments by advising on robust methodology and delivering practical support.
Our Services in Credit Analytics
Foundational Service
Model Development & Validation
Development of credit risk models covering:
-
Application scoring
-
IFRS 9 ECL and SICR / Staging
-
IRB risk parameters: PD, LGD, EAD
-
Stress testing within IFRS 9 and IRB frameworks, including scenario design and Macro/PD/LGD satellite model integration.
-
Demo for example on VAR:
→ Read more
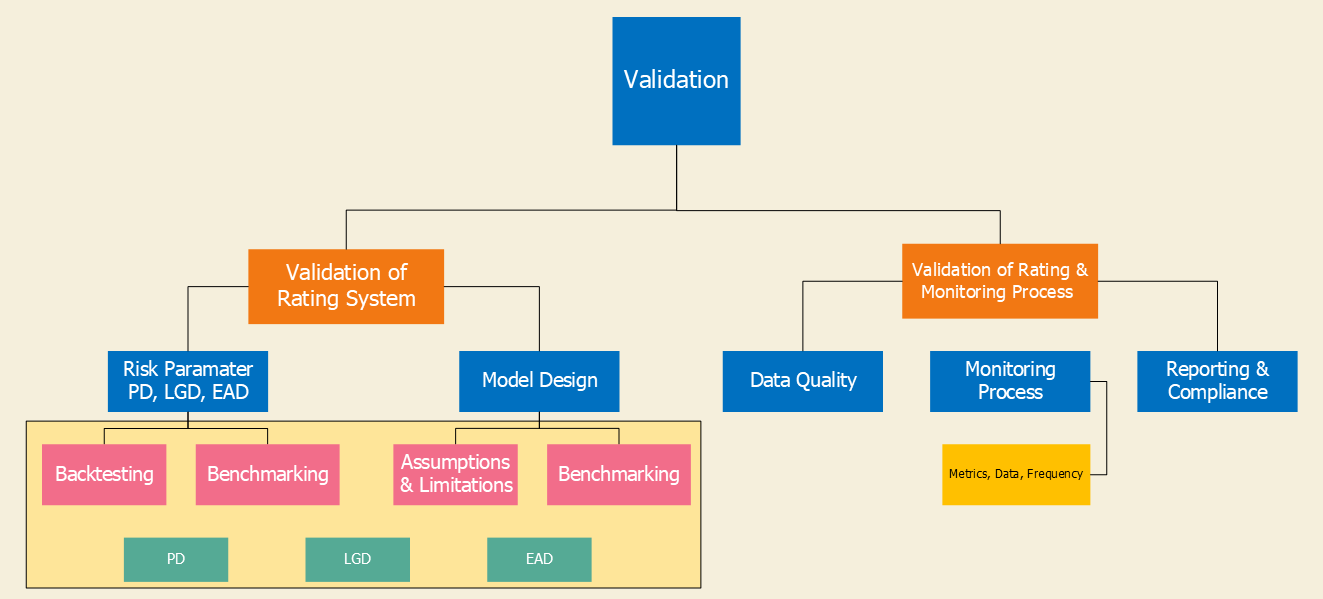
Validation support includes:
-
Validation of PD, LGD, and EAD models on a cyclical basis
-
Testing of model predictions through backtesting, performance, and stability analysis
-
Benchmarking against challenger models
-
Feedback on gaps in model monitoring and shortfalls against regulatory expectations
Supporting Capability
Model Performance and Profitability Analytics
Evaluation and enhancement of credit model performance, with a focus on risk-adjusted profitabiliy and CLV - currently shown through the Credit Customer Value Analytics page.
Our support includes:
-
Boosting PD and LGD model performance through targeted model enhancements.
-
Integration of profitability aspects into development and validation.
-
Feature engineering to identify stronger predictors.
-
Assessment of alternative data sources for emerging risk capture.
-
Use of machine learning methods.
Emerging Area
Credit Portfolio Risk Analytics
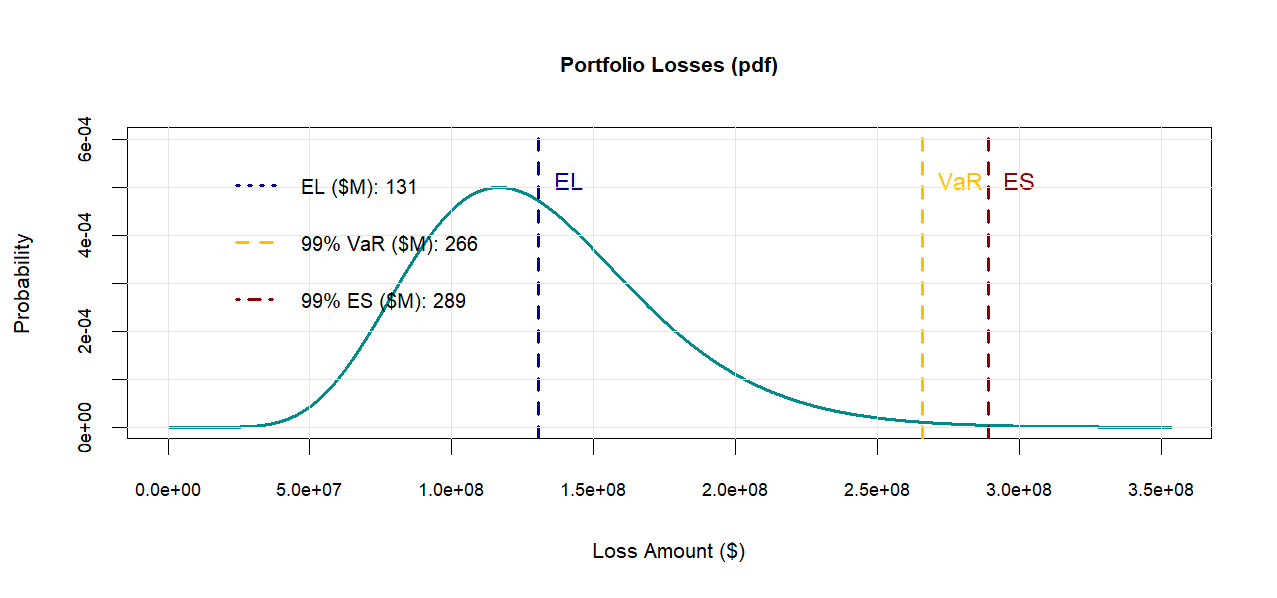
Specialised support for selected credit portfolio risk topics, including credit loss distributions, portfolio segmentation, and risk-adjusted performance.
Available on a focused engagement basis, supported by prototype development and case study work.
- Credit Loss Distributions.
- Segmentation of customer groups.
- Credit Portfolio Vulnerabilities
Supplementary Services
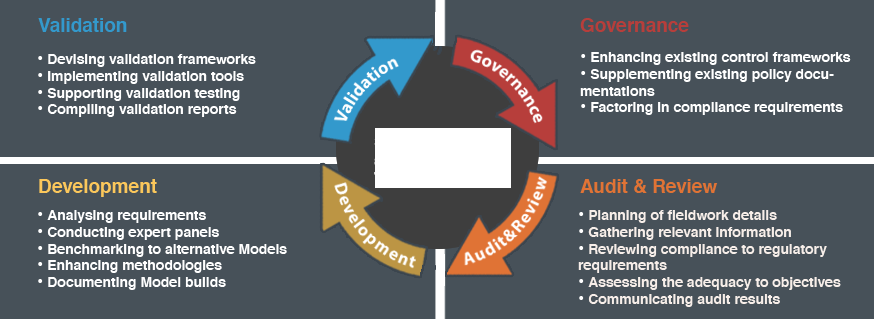
MODEL RISK REVIEW & AUDIT
Independent review of model risk frameworks, governance, and controls.
Our support includes:
-
Identification of control gaps and remediation recommendations
-
Audit readiness and regulatory engagement support
-
Assessment of governance guidelines and documentation
-
Model inventory review and risk-tiering
Tip: Did you know, model risk review is designed to deliver fast, high-impact insight to CROs, audit functions, and senior management:
-
Model design and data limitations
-
Calibration bias and inadequate model outputs
-
Shortcomings in regular validation
-
Regulatory compliance gaps, including SS 11/13 and SS 3/18
Prototypical Programming & Code Testing
Supporting model development and validation through working code, not only conceptual advice.
Our support includes:
-
Prototype development using the R ecosystem and statistical libraries
-
Source code testing and reproducibility checks
-
Code documentation for internal governance and audit trails
-
Automation of reporting and monitoring routines
This service helps institutions move from model concept to working implementation with clear, auditable code.
→ BACK
